Financial Advice
Savings & Investments

If your fixed rate ends in the next 12 months, you have already been handed a decision date. The advice now being repeated across UK consumer media is to start six months before the deal ends, secure a new rate, and switch to a cheaper one if the market falls before completion.
That advice is right for a UK resident with a UK credit file and a high street lender. It leaves no margin for anyone else.
A remortgage arranged from abroad typically takes 16 to 24 weeks. Income in a foreign currency has to be documented and discounted, lender country lists have to be checked, and non-resident offers often expire faster than resident ones. Start at six months and you have a few weeks of slack. Start at three and you are likely to spend time on the standard variable rate.
The review puts your own dates and numbers against that timeline, and tells you plainly whether securing a rate now is the right move.
The Bank of England held the base rate at 3.75% on 17 September 2026, but three of the nine Committee members voted for a rise. The next decision is due on 5 November.
Markets are pricing in around four rises by the end of 2027. Average two-year and five-year fixed rates sit just under 6%, with the most competitive deals from roughly 4.6%, while standard variable rates run at 6 to 7%.
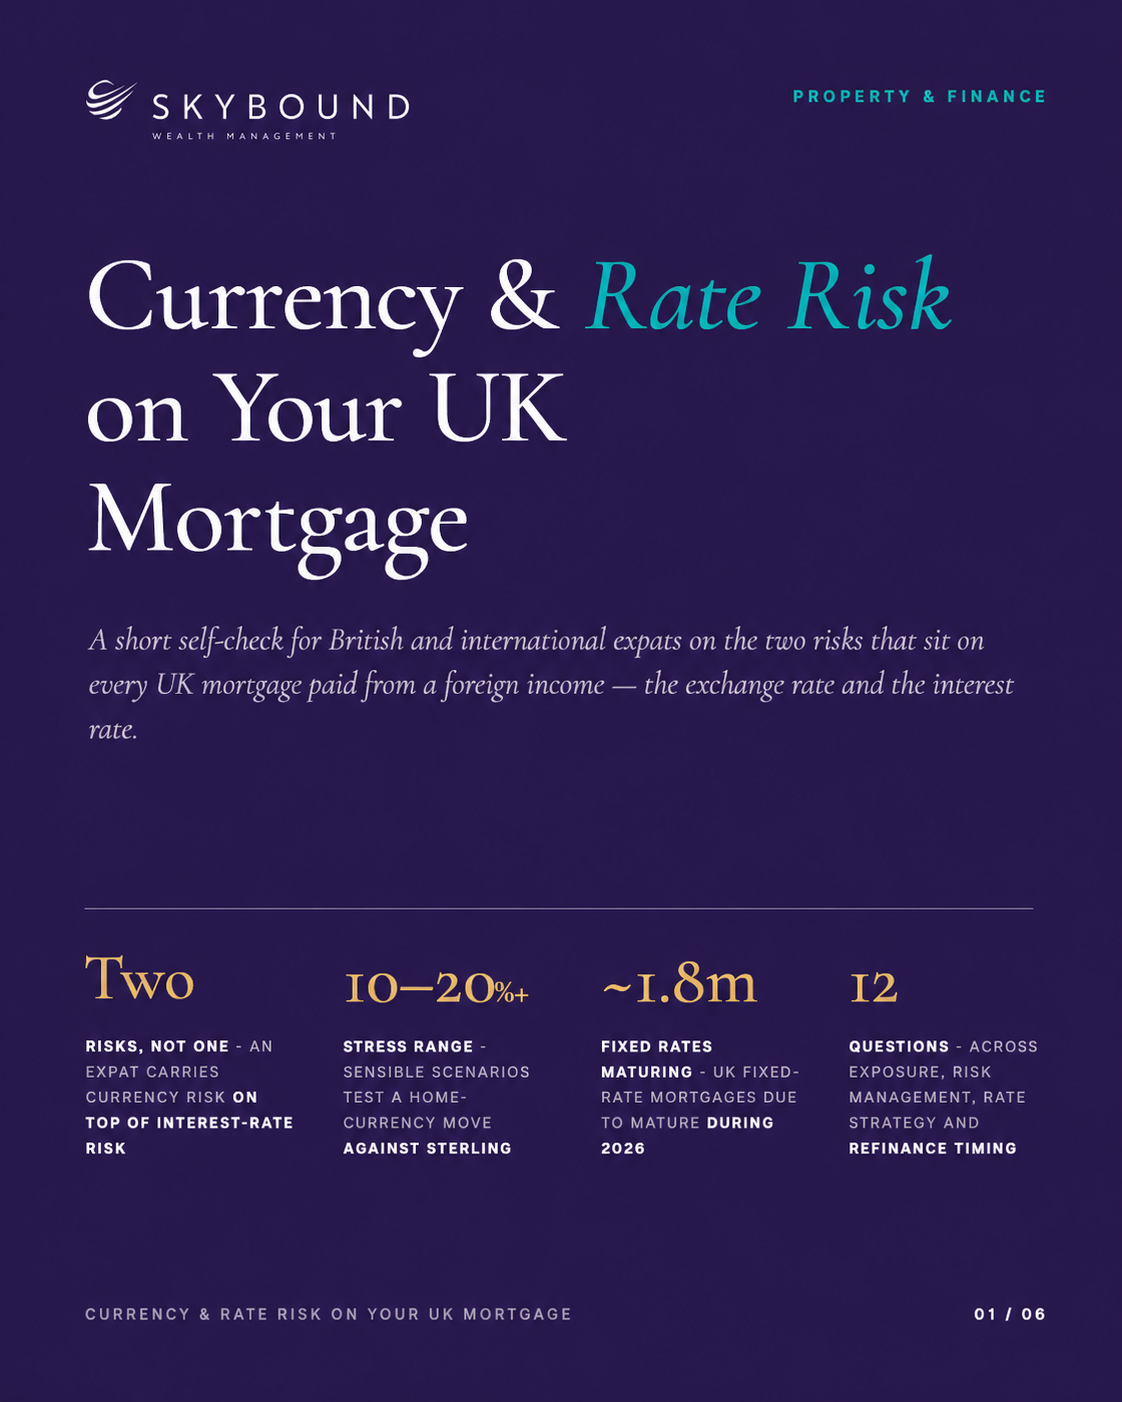
Around 1.8 million UK fixed-rate deals mature in 2026, with another wave in 2027. Rate expectations are those of markets and economists, not a Skybound forecast. Correct as at 20 October 2026.
When your lender will secure the next rate, how long your case takes from where you live, and the date you need to start to avoid the standard variable rate.
A whole-of-market view of the lenders that accept your country, your currency and your income type, with the monthly payment at the rate you could secure now against the rate you would revert to.
What reserving a rate commits you to, and what it does not. Most lenders will hold a rate ahead of expiry and let you switch to a cheaper deal if the market falls before completion.
Higher rates mean higher stress rates, so the same rent covers a smaller loan. We re-run your rental cover before your lender does, while there is still time to adjust the loan or the structure.
"Six months is soundadvice for a borrower in Manchester with a high street lender. For a client inDubai, paid in dirhams, with a lender in Jersey, six months is the day theclock starts. I would rather have that conversation in October than in March."
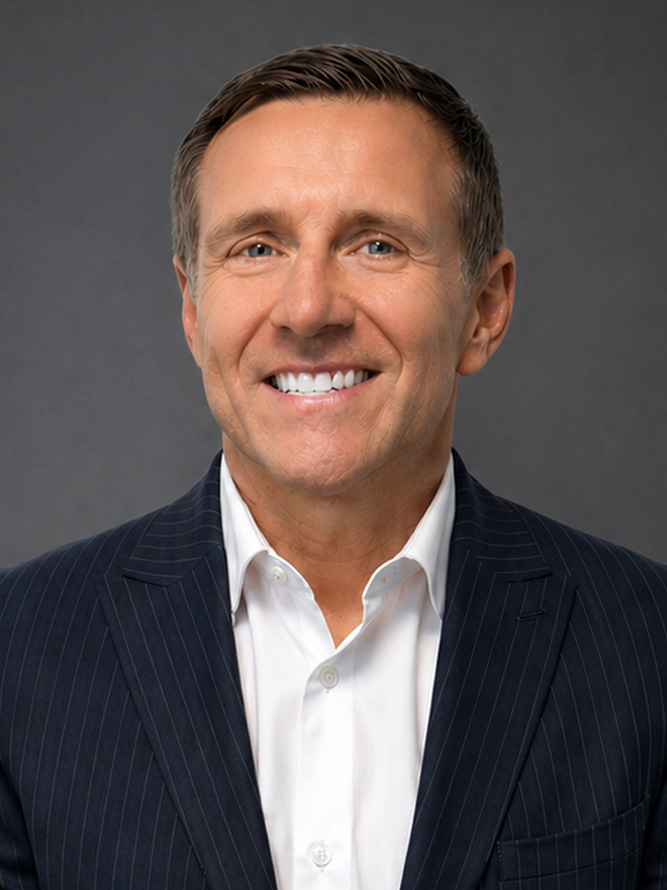
Kieron Franklin
Group Head of Property & Finance

Kieron Franklin is a senior property and finance leader with more than 30 years of international experience across the UK, UAE, Hong Kong, Jersey, and Saudi Arabia. He joined Skybound Wealth Management in 2026 to build and lead the firm's dedicated property and finance division, serving UK-resident and expatriate clients who need joined-up property, lending, and financial planning advice.
Kieron leads Skybound Property & Finance, the division that arranges UK residential and buy-to-let lending for expats and international clients, alongside UK lending for UK residents. He brings 30 years of senior international banking, including roles at HSBC Bank International, RAKBANK, Commercial Bank of Dubai and Saudi Awwal Bank, and holds an MBA from the University of Liverpool and CeMAP with Distinction.
Share when your current rate ends, where you live, how you are paid and roughly what you owe. That is enough for us to map the timeline and shortlist the lenders that fit.
We confirm which lenders will reserve a rate for your case and how far ahead, prepare the application pack for a non-resident file, and secure the rate as early as the lender allows.
The new deal starts the day the old one ends, with no spell on the standard variable rate. If rates improve before completion, we move you to the better deal where the lender permits.
Tell us when your current rate ends and where you live. Kieron or a member of the Property & Finance team will come back within one working day with a realistic timeline and a time for the review.
Living in the UK rather than abroad? The same review is available through our UK lending specialist.
Kieron's lending experience sits inside a firm built for people who live across borders. The mortgage is arranged by Property & Finance; the resources behind it are Skybound's.
The questions we are hearing most from borrowers whose fixed rate ends in the next year.
With most lenders, yes. A new rate can usually be reserved several months ahead of the current deal ending, so the new deal starts when the old one finishes. If rates fall in the meantime, most lenders will let you switch to the better deal before completion, sometimes for a small fee. Reservation windows vary by lender, which is one of the things the review confirms for your case.
At least six months before the deal ends, and earlier if your income includes bonus, commission, dividends or self-employed elements. A remortgage arranged from abroad typically takes 16 to 24 weeks, so six months leaves only a few weeks of slack.
You revert to your lender's standard variable rate, currently around 6 to 7%, against competitive fixed deals from roughly 4.6%. On a £300,000 repayment mortgage over 25 years that is roughly £435 a month more, for every month the new deal is not in place.
No. The review does not forecast rates and does not push one product type. It establishes your timeline, the rate you could secure today and what reserving it commits you to, then helps you choose between certainty and flexibility on your own situation.
Yes, and with extra urgency. A rate rise raises the stress rate lenders use to test rental cover, so the same rent supports a smaller loan. On a £300,000 loan tested at 145% cover, moving the stress rate from 5.5% to 6.5% raises the rent required from £1,994 to £2,356 a month. We re-run that test before your lender does.
Yes. Skybound Property & Finance arranges UK lending for UK residents as well as expats, and the same review is available through our UK lending specialist. Use the same form and tell us your country of residence is the UK.

Quarterly reviews, ongoing rebalancing, regular portfolio factsheets — we’re with you for the long haul, adjusting your plan as life evolves.

Manage your investments 24/7 with the Skybound Wealth App offering real-time portfolio views, performance summaries, and seamless adviser access.

Our exclusive SOAR magazine delivers cutting-edge insights, market updates, and strategies, keeping you informed, inspired, and in control.