I spent my playing years moving between clubs and countries, and I have watched plenty of team-mates buy a place in the sun without once asking what it would cost them back home. This piece is about that second half of the story, the tax that waits quietly for you when you sell up in the Gulf and come home.
If you have spent any of your earning years in the Middle East, you will know the pull. The money is good, the tax picture looks wonderfully simple, and a shining new apartment or villa feels like the obvious way to turn a few strong contract years into something solid. For a lot of footballers, and just as many rugby players, golfers and tennis pros who base themselves in the Gulf, buying property there is one of the first big moves they make. The trouble is that the simple story you hear at the point of sale is only ever half the picture. The other half arrives later, when you rent the place out, when you sell it, and above all when you move back to the UK and your whole financial life comes into the UK system.
Why The Gulf Looks So Simple (And Where The Simple Story Ends)
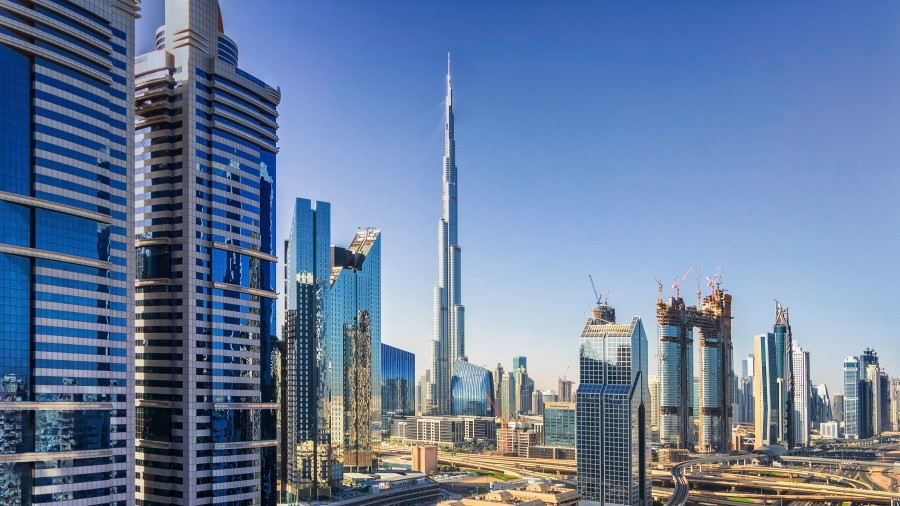
Let us be fair to the Gulf. On its own terms, the tax position really is straightforward. In the UAE there is no personal income tax, no annual property tax of the kind you might expect, no capital gains tax when you resell, and no local tax on the rent you collect. If your entire financial life sat inside the UAE and stayed there, you could genuinely enjoy a property with very little tax friction at all.
That is the part the marketing suite tells you, and it is true. What it does not tell you is that a property does not exist in a vacuum. It exists in relation to you, and specifically in relation to where you are tax resident. The moment a UK-resident person owns that same apartment, a separate tax system takes an interest, whatever the local rules say. So the honest summary is this:
- The UAE side - no personal income tax, no annual property tax, no capital gains tax on resale, no local tax on rental income.
- The UK side - a UK-resident owner is generally taxable in the UK on the rental income and on any gain when they sell, even though the UAE itself does not tax either.
Hold those two facts side by side, because most of the surprises in this area come from people who only ever heard the first one. This is one of those subjects where the way your home country taxes money you earned abroad matters far more than the glossy local headline, and it is exactly the sort of area where you should be taking specialist advice rather than acting on what a salesperson told you across a desk.
What Buying Actually Costs You Up Front
Before we get anywhere near rent or resale, there is the cost of getting in. A common mistake is to budget only for the headline purchase price and treat everything else as a rounding error. It is not.
In Dubai, the up-front buying costs typically run to somewhere around 6-7% of the price. The largest single piece of that is the Dubai Land Department transfer fee, which is 4%. On top of that sit the various registration, agency and administrative costs that make up the rest. None of this is exotic, but it adds up fast on a large purchase, and it is money you will not see again if you sell shortly afterwards.
A few things worth holding in mind about those entry costs:
- Budget the full figure, not the sticker price - on a large purchase, 6-7% is a serious sum, and it comes out of capital, not income.
- The 4% transfer fee is the anchor - it is the biggest single line, so any back-of-envelope sum should start there.
- Costs are sunk on day one - if you buy and then sell again quickly, those entry costs are gone, which quietly raises the bar the property has to clear before you are ahead.
For an athlete this matters more than it does for the average buyer, because your timeline is rarely open-ended. A contract might be three years. A move might come out of nowhere. If there is a real chance you will be selling inside a handful of years, those entry costs deserve to sit at the very front of your thinking, not the back.
{{INSET-CTA-1}}
Off-Plan Versus Completed: Two Different Bets
When you buy in the Gulf you will usually face a choice between off-plan, meaning a property that is still to be built, and completed, meaning something you can walk into today. They are not just two prices for the same thing. They are two genuinely different bets, and the right one depends entirely on your circumstances.
Off-plan tends to be sold on a payment plan, where you put money in across the build rather than all at once. That can suit a player who wants to commit while the contract income is flowing, and the entry price is often lower. But you are buying a promise. You are exposed to whether the development actually completes, whether it completes on time, and whether the finished product matches what you were shown. Your money is committed long before you can rent the place out or live in it.
Completed property is the opposite trade. You pay more, and you pay it sooner, but you get certainty. You can inspect what you are buying, rent it or sell it straight away, and there is no build risk hanging over you.
A simple way to hold the two apart:
- Off-plan - lower entry price, staged payments, but completion and developer risk, and no income or usable asset until it is finished.
- Completed - higher and earlier outlay, but you can see what you are buying and put it to work immediately.
- Your timeline decides - a longer, patient horizon can carry off-plan risk more comfortably than a career stage where you might need to move or sell at short notice.
The cross-border twist is that whichever route you take, the UK question does not go away. When and how the property eventually produces income or a gain still gets looked at from the UK side once you are UK resident, whether you bought a finished villa or waited two years for a tower to top out.
Rented Out Or Left Vacant: The Income Question
Once you own the place, you face a second fork. Do you rent it out, or leave it sitting empty for your own use and future sale?
Leaving it vacant feels clean and simple. No tenants, no wear, ready whenever you want it. But an empty property is not free to hold. Your capital is tied up in it, doing nothing, when it could be spread across other things. There are running costs and service charges to pay whether anyone is living there or not, and an empty apartment earns you precisely nothing while it waits.
Renting it out changes the picture in two directions at once. On the upside, you get income. On the downside, that income is what triggers the cross-border complication. Locally, the UAE does not tax the rent. But a UK-resident landlord is generally taxable in the UK on overseas rental income, and that is the part that catches people out, because they assume a tax-free country means tax-free rent, full stop. It does not, once you are UK resident.
Some things to weigh before you decide:
- Vacant - simplest to manage and always available to you, but it ties up capital and still carries service charges while earning nothing.
- Rented - produces income, but that income is generally within reach of the UK tax system for a UK-resident owner.
- Records matter either way - if the place is ever let, keep a clean record of income and costs from day one, because the UK side may need it later.
- Do not assume symmetry - tax-free locally does not mean tax-free at home, and that gap is where the nasty surprises live.
I am deliberately not going to put a UK figure on any of this, because the answer depends heavily on your personal circumstances. What I will say plainly is that if you are letting an overseas property while you are, or expect to become, UK resident, that is a conversation to have with a specialist before the first rent cheque lands, not after.
The UK Side Nobody Mentions At The Signing
Here is the heart of it. The single biggest reason athletes get caught out is that the UK tax treatment of a foreign property is barely mentioned at the point of purchase, because the people selling to you are, quite reasonably, focused on their own country’s rules.
But the UK does not stop caring about your money just because it is parked abroad. For a UK-resident owner, two things are generally true and worth stating cleanly:
- Rental income from the overseas property is generally taxable in the UK.
- Any gain when you sell the property is generally taxable in the UK.
Both of those hold even though the UAE imposes no such taxes locally. The local absence of tax does not switch off the UK’s interest. This is the exact spot where the two-country nature of the whole thing becomes unavoidable, and it is why I keep coming back to the same point: you need to understand the tax treatment in both the country where you bought and the country you call home.
I want to be careful here, because this is technical and it turns on your specific facts. I am not going to assert precise UK liabilities, rates or reliefs, because doing so without knowing your full position would be exactly the kind of false certainty this area punishes. What I am confident telling you is the shape of the risk: a UK-resident owner should assume the UK has an interest in both the rent and the eventual gain, and should get that pinned down properly by someone qualified in UK tax before relying on any assumption to the contrary.
When You Sell: The Gain That Follows You Home
Selling up is where the whole thing comes to a head. In the UAE, the resale itself is not hit with local capital gains tax, and that is a real advantage. But if you are UK resident when you sell, the gain is generally within the scope of UK tax, and that is the figure people forget to plan for.
Think about the sequence a typical player goes through. You buy while you are out in the Gulf and not UK resident. The property grows in value over your contract years. Then your career takes you home, you become UK resident again, and only then do you sell. That final step, the disposal, is now happening while you are inside the UK system, and the gain that built up over all those years does not simply vanish because it accrued abroad.
A few practical points to sit with:
- Timing is not a detail, it is the whole thing - whether you are UK resident at the point of sale can matter enormously to how the disposal is viewed.
- The gain can follow you - a profit that felt like a purely local, tax-free win in the Gulf may look very different once you are selling as a UK resident.
- Do not plan the sale in isolation - the decision to sell and the decision about where you are resident are tangled together and should be thought about as one.
- Get advice before you list, not after you complete - once the sale goes through, your options for arranging things sensibly narrow sharply.
This is not a place for rules of thumb picked up in a dressing room. The interaction between where you are resident, when you sell, and how the gain is measured is intricate and depends on facts I cannot see from here. Treat it as a flag to get specialist UK advice well before you put the property on the market, and specialist advice in the country of sale too.
Coming Home: Bringing Your Whole Financial Life Into UK Tax
The property is really just one thread in a much bigger change: what happens to your entire financial picture when you move back. Returning to UK residence brings your worldwide income and gains into UK tax, not just your UK earnings. That is a significant shift, and it is easy to underestimate after years in a place that taxed almost nothing.
In practice, the moment your tax residence shifts back to the UK becomes one of the most important dates in your financial life, and it deserves to be planned around rather than stumbled into. Everything you hold abroad, the Gulf property included, comes into view.
Some of the moving parts to think about as you plan a return:
- It is not just the property - overseas savings, investments and other income sources all come into the frame once you are UK resident on a worldwide basis.
- Sequencing matters - the order in which you sell assets, move money and change your residence can make a real difference, and it is worth mapping before you act.
- A clean picture beats a scramble - knowing what you hold, where, and in what currency before you land is far better than reconstructing it under pressure afterwards.
- Newly arriving is a special case - the rules for someone coming to the UK after a long stretch of non-residence are fact-specific and change over time, so they need checking against your exact history rather than assumed.
I keep the property and the wider return in the same breath deliberately, because in real life they happen together. The player who sells the villa is usually the same player packing up a life abroad, and the tax questions land at once. Planning one without the other is how people get caught.
Currency: The Silent Third Party In Every Deal
There is a risk in all of this that has nothing to do with tax at all, and it gets ignored far too often. If your property, your rent and your eventual sale proceeds are all sitting in dirhams, then the pound value of everything you own out there moves every single day, whether you are watching or not.
Holding wealth in a currency you do not spend in is a real exposure, not a technicality. You might sell your property for a healthy figure in local terms and still find the pound value has moved against you by the time you convert and bring the money home. Or it might move in your favour. Either way, you are carrying that risk whether you meant to or not.
Things worth being honest with yourself about:
- Your real yardstick is the pound - if you plan to live in the UK, what matters is what your overseas assets are worth in sterling, not in local currency.
- The sale and the transfer are two events - agreeing a price is one thing, actually getting the money home at a rate you are happy with is another.
- Large sums amplify small moves - on a property-sized amount, even a modest shift in the exchange rate is a meaningful figure worth planning around.
Golfers and tennis players who earn prize money in a spread of currencies will recognise this instantly, because they live it every season. For a footballer or rugby player whose overseas life is more concentrated, it can be less obvious, right up until the day you go to move a large sum and realise the rate is doing something you did not plan for.
{{INSET-CTA-2}}
Two Tax Systems, One Property: Why You Need Advice In Both
If there is one idea I want you to take from all of this, it is that a cross-border property is subject to two tax systems at once, and you cannot understand your position by looking at only one. The Gulf rules tell you what happens locally. The UK rules tell you what happens at home. Your actual position is the combination of the two, and that combination is specific to you.
That is why I have deliberately not handed you neat UK figures in this piece. The honest answer to most of the precise questions is that it depends on your residence history, your timing, your wider finances and rules that can move, and presenting any of that as settled would be doing you a disservice.
What a good plan looks like instead:
- Advice in the country of purchase - so you understand the local mechanics of buying, holding and selling.
- Advice in your home country - so you understand how the same property is treated once you are UK resident.
- Someone joining the two up - so the picture is coherent rather than two half-answers that do not meet in the middle.
- Early, not late - the most valuable conversations happen before you buy, before you let, and before you sell, while your choices are still open.
Whatever your sport, if you are turning some of your Gulf income into bricks and mortar, this is the discipline that protects you. Not avoiding property, just going in with both eyes open and both tax systems understood.
How Professional Planning Support Actually Fits
People sometimes assume an adviser’s job here is to sell them something, and in this area that could not be further from what helps. The value is in the thinking, the timing and the coordination, not in a product.
- Framing the right questions - much of the danger comes from not knowing what to ask in each country, and good support starts by getting the questions right.
- Coordinating the specialists - you may need local expertise and UK expertise, and someone has to make sure they are pointing at the same picture.
- Sequencing the big moves - when you sell, when you move money, when your residence changes, all of it benefits from being planned as one sequence rather than a series of reactions.
- Keeping you honest on currency - a plan that ignores the pound value of your overseas wealth is not a plan, and support here means keeping that front of mind.
- Protecting you from false certainty - the real skill is knowing where the settled facts end and the fact-specific questions begin, and steering you to proper advice on the second.
This is why serious players often seek a conversation, not a product.
The Soft But Decisive Next Step
I have been the player who moved country without thinking three steps ahead, so I know how easy it is to let this slide until it becomes urgent.
- I would rather you had the two-country picture clear in your head before you sign anything than after you have committed.
- I would rather flag honestly where something is fact-specific and needs a specialist than pretend I can give you a tidy number that would not survive contact with your real circumstances.
- I would rather help you plan the timing of a sale and a move home calmly, in advance, than watch it happen in a rush.
If you own a place in the Gulf, or you are about to buy one, the sensible next step is a conversation to map out what applies to you and what to line up in each country. No pressure, no product, just a clear look at where you stand.
Final Takeaway
This is not about talking you out of owning property in the Middle East. It is not about scaring you with tax you may never owe. And it is not about pretending I can hand you precise UK figures from a distance, because I cannot and neither can anyone honest.
It is about going in with your eyes open. It is about understanding that the wonderfully simple Gulf tax picture is only one side of a two-sided story. It is about knowing that a UK-resident owner is generally taxable at home on the rent and the gain, that coming back brings your worldwide finances into UK tax, and that currency quietly rides along with it. And it is about doing what I watched too many team-mates skip: getting proper advice in both countries before you act, not after. Do that, and the place in the sun stays a good decision instead of becoming a surprise.