The Pension Blind Spot: 25 Checks for British Expats Ahead of April 2027
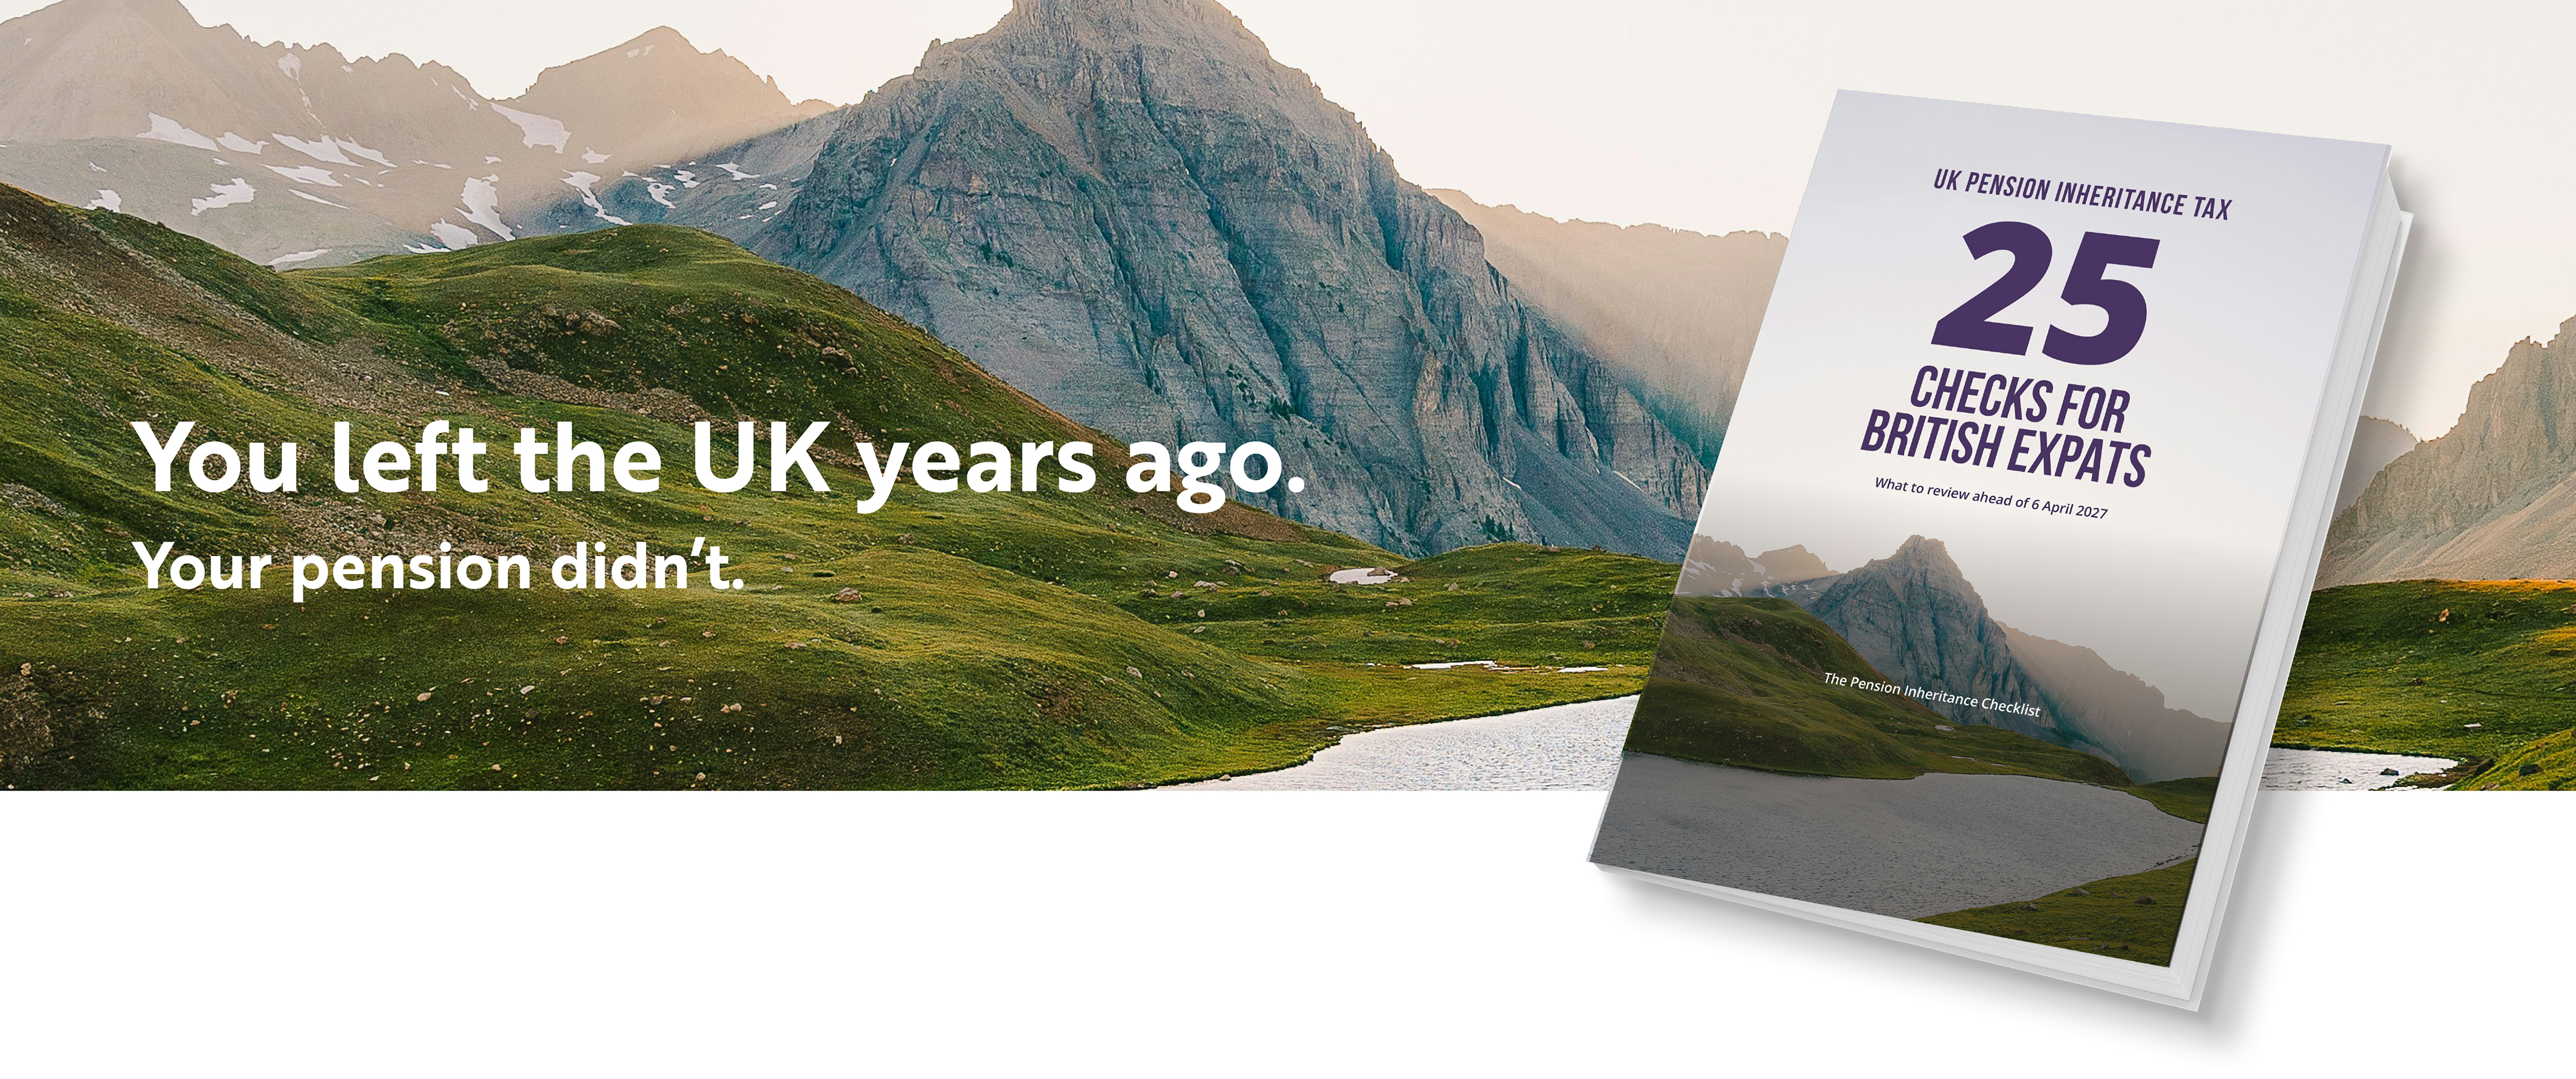
Before most unused pension funds and death benefits come within UK inheritance tax on 6 April 2027, Skybound Wealth's new 25-point checklist shows British expats why a UK pension can remain in scope from abroad, and what to review first.
Why a UK pension can remain in scope when you live abroad
How much an inheritance tax bill can change, in a hypothetical example
What our pensions and tax experts say to check first
What is inside the 25-point checklist, and where to download it
How to book a complimentary introductory review
A Change Already in Law, and a Date Already Set
The change was legislated in the Finance Act 2026, which received Royal Assent on 18 March 2026, and the Budget of 28 October 2026 left the start date unchanged. Four figures frame what it means:
6 April 2027: the rules apply to deaths on or after this date.
40%: the standard inheritance tax rate on value above the nil-rate bands. The basic band is £325,000, with up to £175,000 more where a home passes to children or grandchildren (conditions apply, and it is reduced for estates above £2 million). Both bands are frozen until April 2031.
10,500 estates: the government's modelling estimate of estates that will have an inheritance tax bill in 2027-28 where previously they would not, with around 38,500 estates paying more.
£34,000: the expected average rise in the inheritance tax liability where pensions are included. These are national estimates, not a forecast for any one family. HMRC says they are static, do not take into account potential behavioural changes, such as tax planning or drawing down pension funds faster, and should be viewed as a maximum.
Why Living Abroad Does Not Settle It
Since April 2025, UK inheritance tax has turned on residence rather than domicile. You are a long-term UK resident if you were UK resident for at least 10 of the previous 20 tax years, and the status can last for up to 10 tax years after you leave.
If you are a long-term UK resident, your worldwide assets are in scope. If you are not, most of your non-UK assets are outside UK inheritance tax, but a pension held in a UK-established scheme can remain in scope.
One of the checklist's hypothetical worked examples shows what that means. David has lived in Dubai since 2012 and is no longer a long-term UK resident. His UK estate, a £300,000 rental flat and £40,000 in savings, would pay £6,000 in inheritance tax under today's rules. From 6 April 2027, with his untouched £500,000 UK pension included, the bill for his estate rises to £206,000. On these assumptions, David's UAE assets are outside UK inheritance tax because he is no longer a long-term UK resident. His UK pension remains in scope. Every assumption is set out in the checklist.
Couples can be caught out too. Where the spouse who dies is a long-term UK resident and the survivor is not, the spouse exemption is capped at £325,000, cumulative over a lifetime across all spouses and civil partners, so leaving everything to a spouse may not be tax-free. An election can lift the cap, but it cannot be revoked and can bring the survivor's worldwide assets within UK inheritance tax.
Two Views From Our Experts
Carla Smart, Group Head of Pensions:
“Your pension needs to support your retirement first. Before making changes because of the inheritance tax rules, check how they affect your family, what income you need and whether any action could create other tax or costs.”
Shil Shah, Group Head of Tax Planning:
“Many expats assume that living somewhere with no income tax or inheritance tax puts their UK pension beyond HMRC’s reach. From April 2027, that will not hold for most pensions in UK schemes. It is your residence over the past 20 years, not your passport, that decides what else is in scope. And for couples where only one partner has a long UK history, leaving everything to a spouse may not be the tax-free option they assume.”
Inside the Checklist
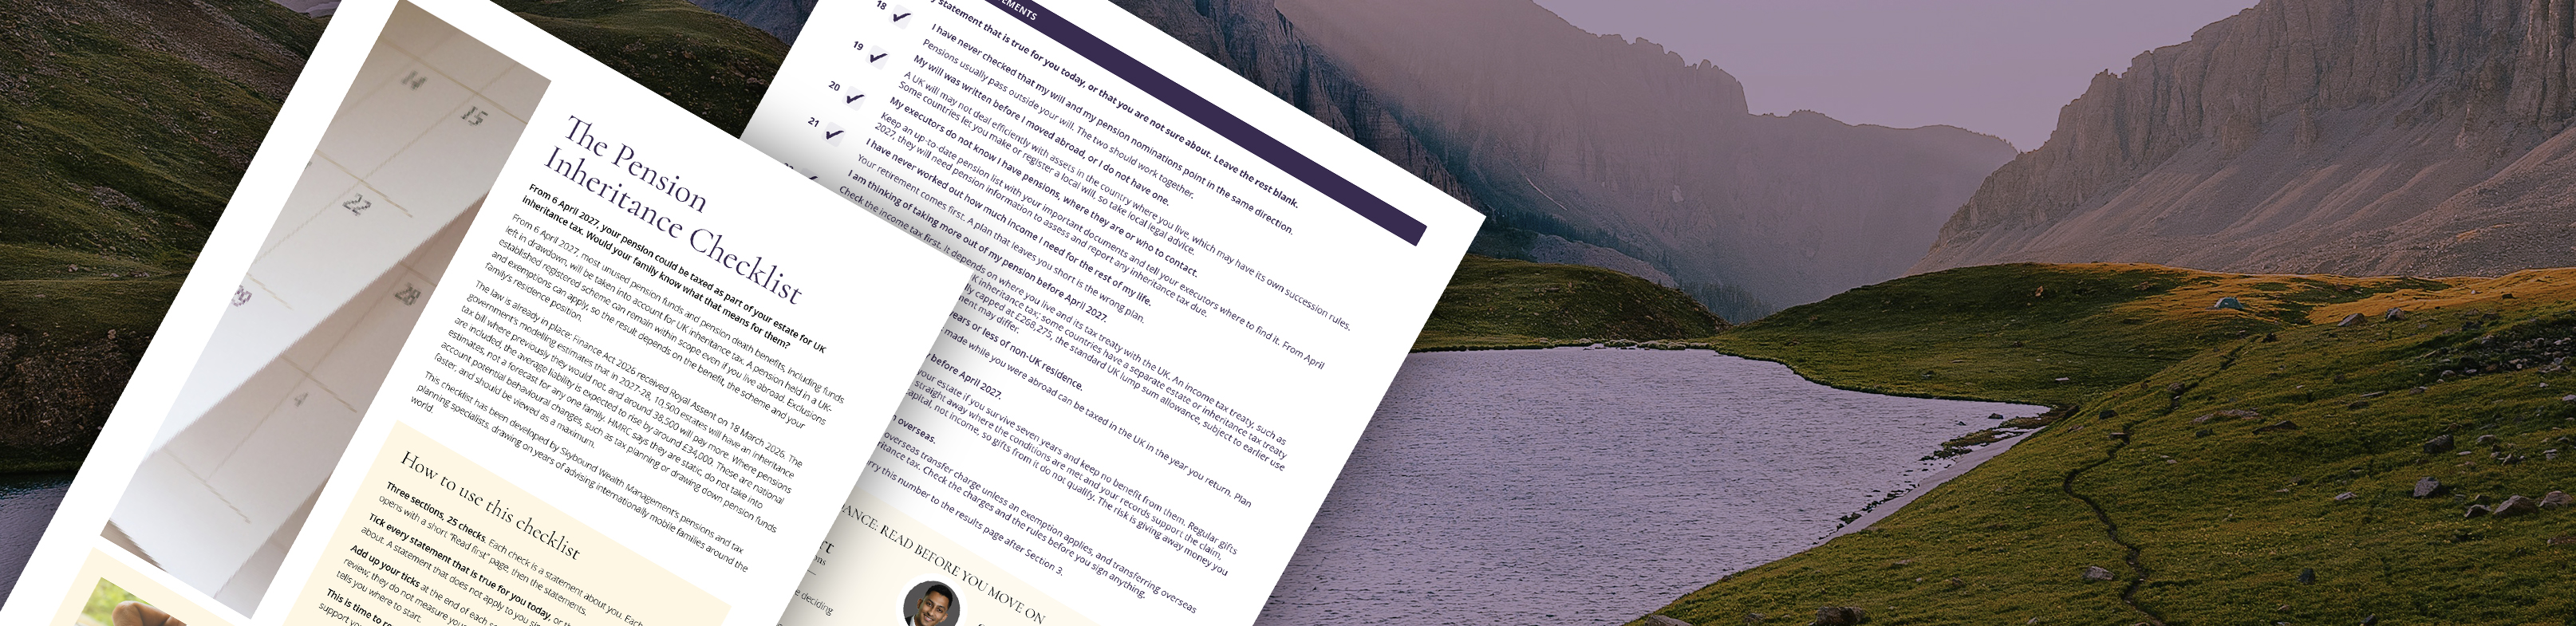
The checklist sets out 25 checks in three areas, with guidance from our pensions and tax experts in every section. Each check is a plain statement about you: tick it if it is true, or if you are not sure. Your ticks identify the questions to review; they do not measure your tax exposure.
What you have and what may be affected: every pension you hold, where each scheme is established, and your residence status.
What your family could receive: a spouse versus children, why age 75 matters, and how the tax would be paid.
What to review before making changes: nominations, wills, withdrawals, gifts and transfers.
It also includes a step-by-step guide to what happens to a pension on death under the new rules, an action pack of questions to ask each pension provider, and a technical appendix with three worked examples, every assumption stated, and a clear list of what is settled and what HMRC has still to confirm.
Review, Not Rush
The months before April 2027 are time to review, not a deadline to move money. Withdrawing more than you need, giving money away too early or transferring a pension overseas can each create costs of their own, from income tax to a 25% overseas transfer charge on some transfers.
Some of the detail is still to come. HMRC has still to publish its guidance on international issues, and final guidance is due in spring 2027. We will update the checklist as each is published. For the full picture, including the exclusions, how income tax applies and every assumption behind the worked examples, download the checklist.
{{INSET-CTA-1}}
The checklist is free to download. It sets out all 25 checks, the worked examples and guidance from our experts, and we will update it as HMRC publishes further guidance.
Key Points to Remember
From 6 April 2027, most unused pension funds and pension death benefits are taken into account for UK inheritance tax, subject to exclusions and exemptions.
Pensions in UK-established registered schemes can remain in scope whether or not you are a long-term UK resident.
You are a long-term UK resident if you were UK resident for at least 10 of the previous 20 tax years; the status can last up to 10 tax years after leaving.
Where the spouse who dies is a long-term UK resident and the survivor is not, the spouse exemption is capped at £325,000, cumulative over the giver's lifetime across all spouses and civil partners, and the election that lifts the cap cannot be revoked and can bring the survivor's worldwide assets within UK inheritance tax.
The months before April 2027 are time to review, not a deadline to move money.
FAQs
Does the UK pension inheritance tax change apply if I live in the UAE?
What is a long-term UK resident?
Should I take money out of my pension before April 2027?
Disclosure
This article is for information only and does not constitute financial, tax or legal advice. Tax treatment depends on individual circumstances and may change in the future. Rules as at 10 November 2026.Update log:November 2026: first published, with version 1.0 of the checklist. Rules checked 10 November 2026, after the UK Budget of 28 October 2026.
Find Your Pension Blind Spot Before April 2027
Download the checklist and work through it at your own pace, then take your answers to your adviser or pension provider.
See which of your pensions may stay within UK inheritance tax from abroad
Check how the new rules could change what your spouse or children receive
Get a ready-made list of questions to put to each pension provider
Know what is already settled and what HMRC has still to confirm
Understand your provider’s rules for foreign addresses
Compare 401(k) and IRA fees
Review tax implications
Confirm the IRA custodian supports foreign residency
Evaluate investment preferences
Consider currency needs
Understand Roth conversion implications
Evaluate long-term residency and retirement goals
Consult advisers familiar with cross-border planning
Ordered list
Item 1
Item 2
Item 3
Unordered list
Understand your provider’s rules for foreign addresses
Compare 401(k) and IRA fees
Review tax implications
Confirm the IRA custodian supports foreign residency
Evaluate investment preferences
Consider currency needs
Understand Roth conversion implications
Evaluate long-term residency and retirement goals
Consult advisers familiar with cross-border planning
Book Your Complimentary 30-Minute Pension Inheritance Review
A complimentary, confidential, no-obligation introductory review with one of our experts to map the facts and identify your priorities: which of your pensions may be in scope, the residence questions to answer, and what to review first. It is not personal tax advice or a product recommendation; any recommendation would follow our normal fact-find, suitability and advice process.
Book Your Complimentary 30-Minute Pension Inheritance Review
A complimentary, confidential, no-obligation introductory review with one of our experts to map the facts and identify your priorities: which of your pensions may be in scope, the residence questions to answer, and what to review first. It is not personal tax advice or a product recommendation; any recommendation would follow our normal fact-find, suitability and advice process.