UK Pensions and Inheritance Tax: What Every British Expat Needs to Know
Will Spires explains how April 2027 UK pension changes bring inheritance tax risks for British expats and why early planning matters.
August 26, 2025

The UK Budget of 28 October 2026 brought announcements affecting savings income, rental property, pensions and business owners. They have different start dates, and the impact depends on your circumstances.
Whether you live in the UK, are based overseas or are planning a future return, a review can help you understand which points are relevant to your financial plans.
A summary of selected measures. Some remain subject to legislation or consultation.
Rates of 24%, 44% and 49% have been announced for UK-taxable savings and property income from 6 April 2027. The property rates apply in England, Wales and Northern Ireland; Scotland has a separate tax framework.
The limit remains within the overall annual adult ISA allowance. Non-UK residents generally cannot make new subscriptions, although existing ISAs can usually be retained. Their tax treatment overseas depends on where you live.
For deaths on or after 6 April 2027, most unused pension funds and certain pension death benefits will enter UK inheritance tax scope. Your inheritance tax status, estate value, applicable exemptions and allowances remain important.
For relevant payments from 28 October 2026, certain otherwise tax-free benefits following a death before age 75 will no longer be taxed solely because the two-year deadline was missed. Other conditions and allowances still apply. This does not reverse the inheritance tax reform.
The Budget announced a reduction in the Business Asset Disposal Relief lifetime limit from £1 million to £500,000 for qualifying disposals from 6 April 2027. A new 10% Founders’ Relief is proposed for qualifying founders and early investors, subject to consultation and final legislation.
If your life or assets span more than one country, the relevant question is how UK rules interact with your circumstances and the tax system where you live.
Available allowances, reliefs and any relevant treaty should be considered before decisions are made.
Shil Shah
Group Head of Tax Planning

28 October 2026
Relevant payments under the pension death-benefit two-year rule change.
6 April 2027
Announced savings and property income rates and BADR changes; pension inheritance tax reform for deaths from this date.
Your own timeline
A future UK return, business disposal or retirement may affect the order in which you review your plans.
Shil Shah, our Group Head of Tax Planning, explains the detail, the dates and what may warrant a review. The guide also covers trusts, high-value UK property and State Pension planning.

Shil Shah is Skybound Wealth’s Group Head of Tax Planning and a Private Wealth Adviser, based in London. He works with clients who live global lives, executives, entrepreneurs, families and professionals who want clear, confident guidance on their wealth, their tax position and the decisions that shape their future.
Shil’s Budget analysis brings specialist tax insight to the announcements. Our team can help you consider the points that matter to your savings, investments, pensions and wider financial plans, taking account of where you live and what you want to achieve.

Tell us where you live, how we can contact you and which part of your financial planning you would like to discuss.
Our team will contact you to understand your enquiry and arrange a meeting with an appropriate adviser.
Discuss the announcements in the context of your circumstances and identify any areas where further advice may be helpful.
Whether you already have financial arrangements in place or are exploring your options, we can start with where you live, what you have planned and what you want to achieve.
Share your details and our team will contact you to arrange a suitable time.
Our team works with British expatriates and internationally mobile individuals to help them understand their options and plan for the future. We bring financial planning and consideration of cross-border tax issues together around your circumstances.
Get clear answers to key post-Budget questions, exploring how changes to taxes, pensions, savings, investments and allowances could affect your finances, and what they may mean for your personal financial plans.
Quarterly reviews, ongoing rebalancing, regular portfolio factsheets — we’re with you for the long haul, adjusting your plan as life evolves.
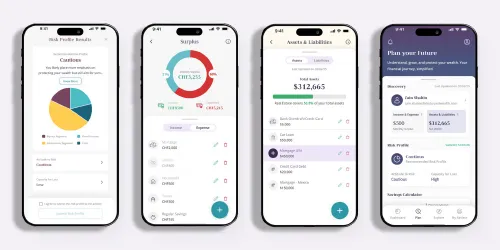
Manage your investments 24/7 with the Skybound Wealth App offering real-time portfolio views, performance summaries, and seamless adviser access.
Our exclusive SOAR magazine delivers cutting-edge insights, market updates, and strategies, keeping you informed, inspired, and in control.